Jackson Thomas
CrossCountry Mortgage
For Clients · Dallas, Texas

Your next chapter, handled like our own.

Buying a home is a big moment for your family. We’ll carry the details, keep you updated every week, and keep our word on your closing date, so you can focus on what’s ahead.

Start Your Pre-Approval →
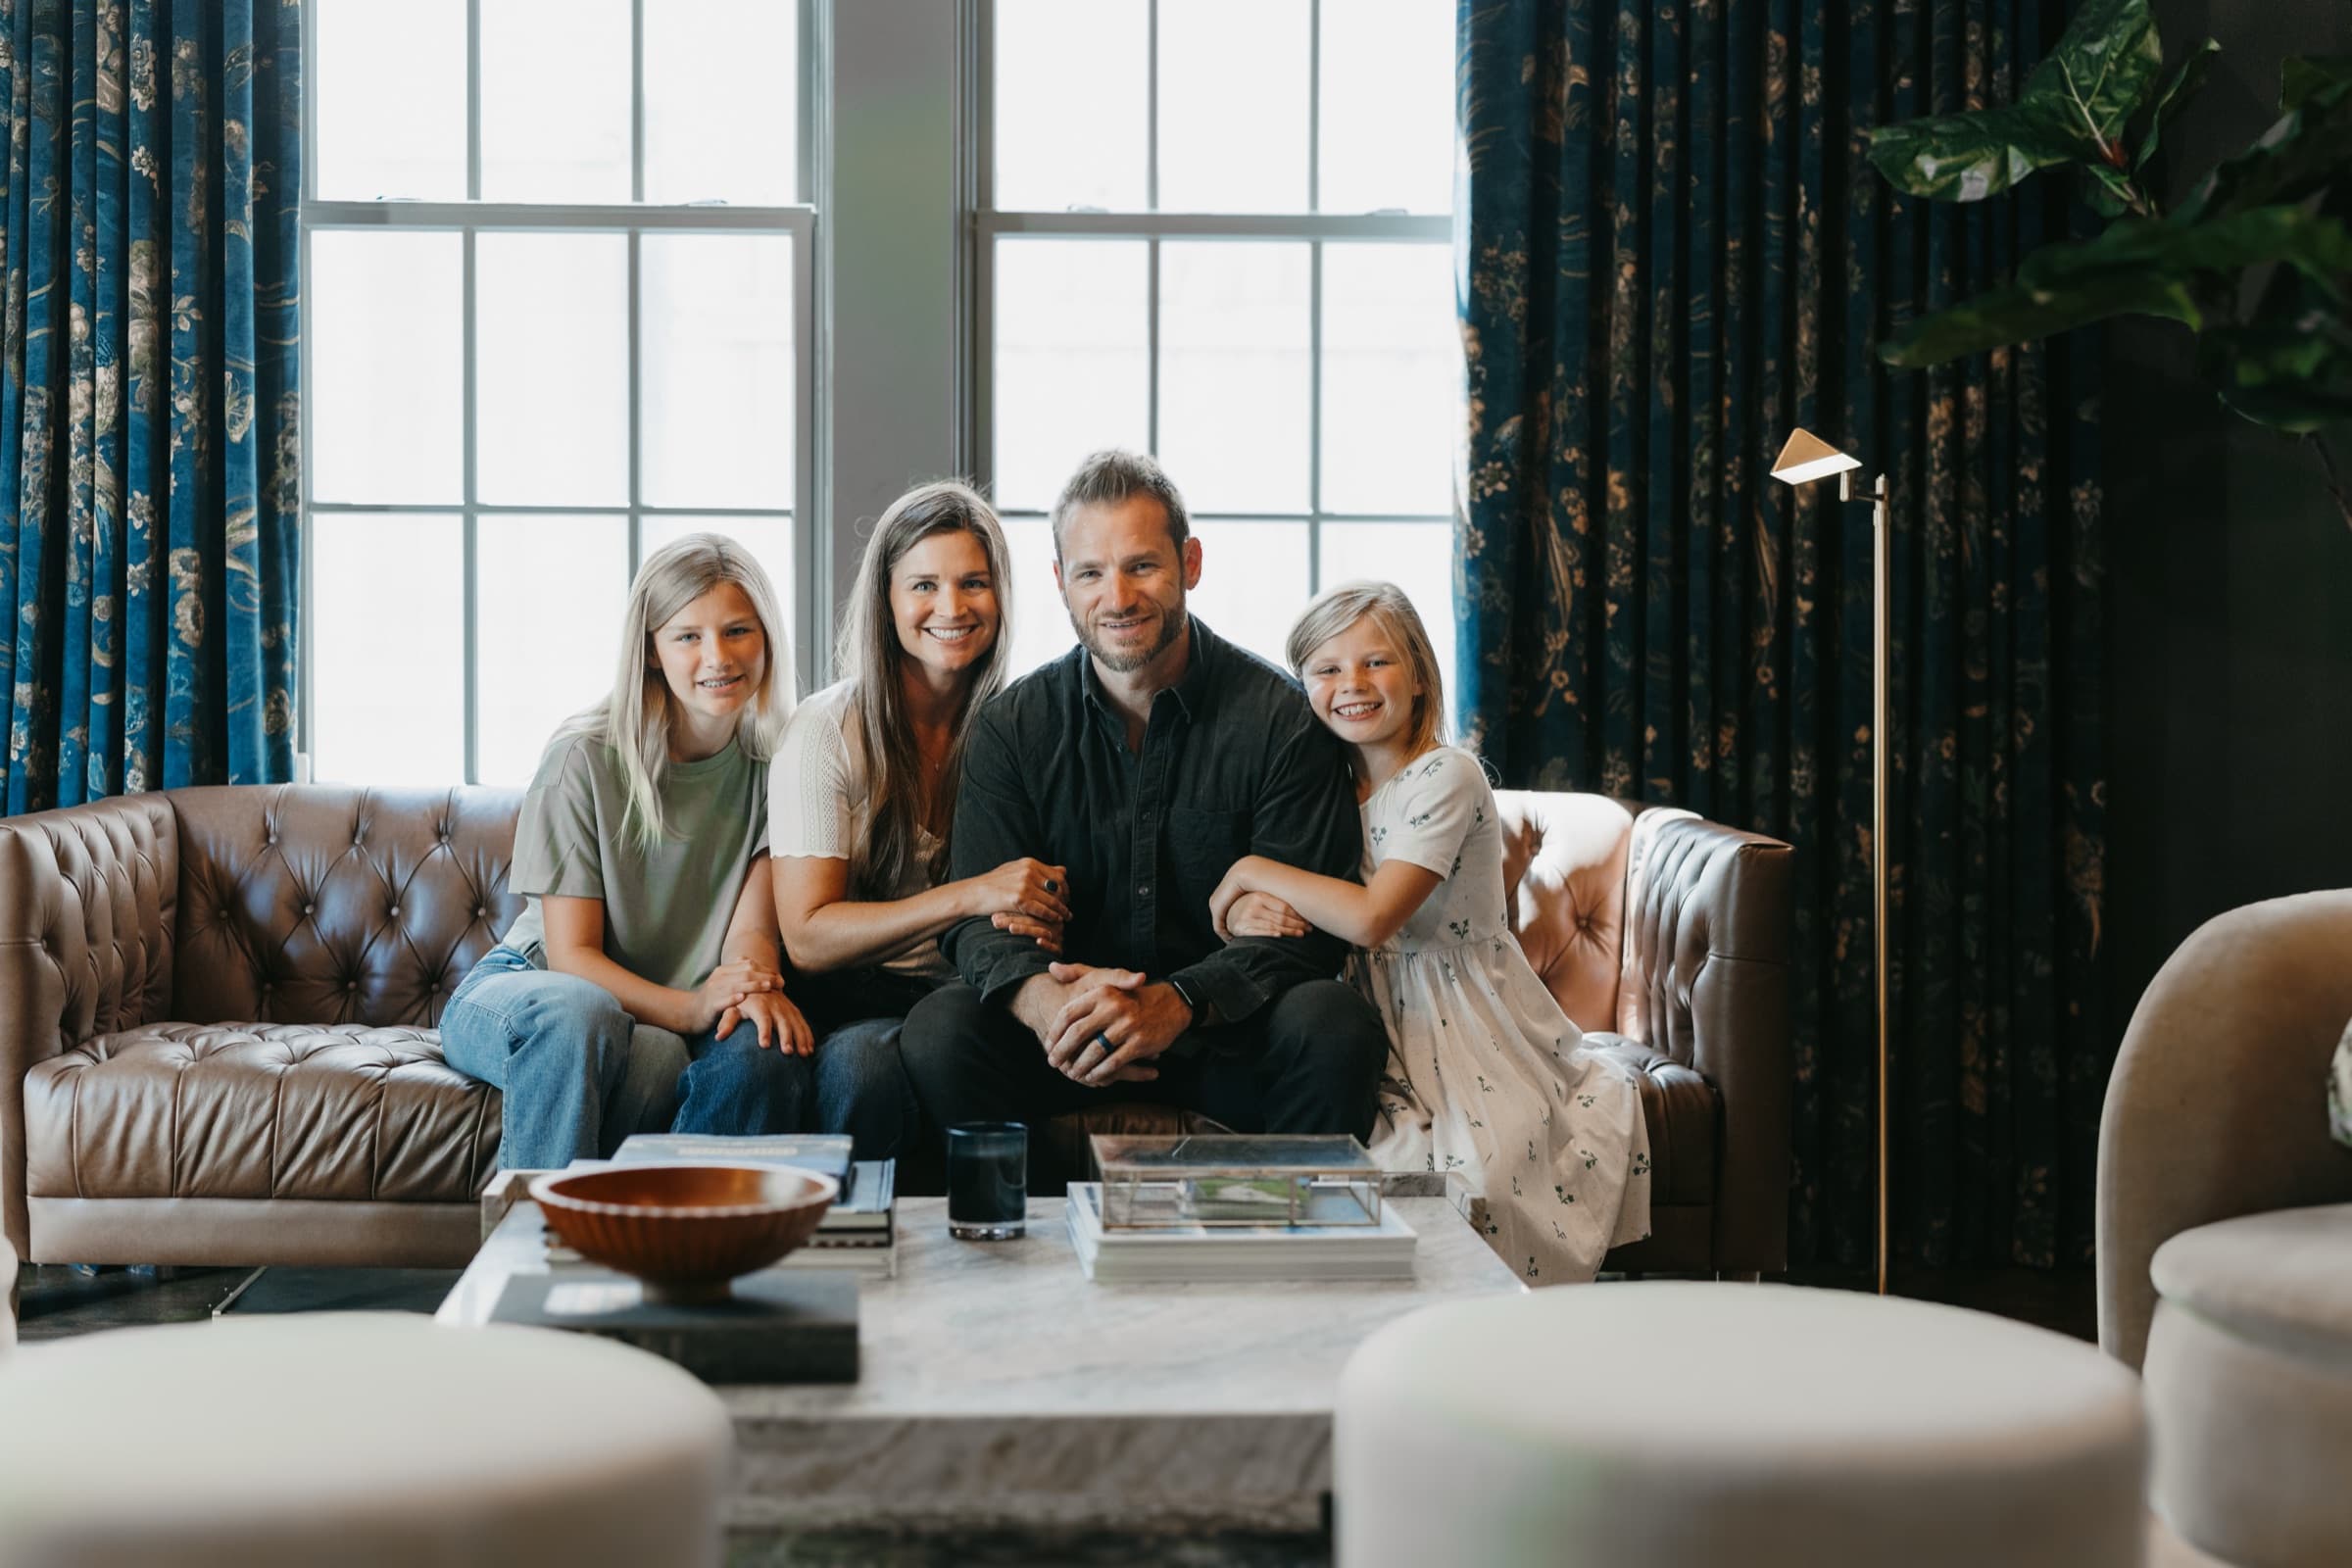
Jackson Thomas with his family
About Jackson & the Team

The reason behind the work.

Before he’s a loan officer, Jackson is a husband and a dad. The standard he keeps at home is the one he brings to every file: show up, keep your word, and finish what you start.

He and his team handle processing, underwriting, and funding in-house, send structured updates every week, and have never missed a closing for a reason within their control.

100%
On-Time Closings
15 days
Avg. Close
30+ Yrs
Family Legacy
Reviews

In our clients’ words.

4.98★
1,314+ verified
reviews
4.96
Experience
4.99
Zillow
4.98
Google
5.0
Facebook
★★★★★
“Jackson did an incredible job of explaining everything to me as a first time buyer, and made the experience as stress free as possible.”
Elizabeth L.
Dallas, TX
★★★★★
“I love working with Jackson and his team! It’s always an easy process and from start to finish I felt genuinely cared for. They do whatever they need to do to get things across the finish line!”
Coleman R.
Experience.com
★★★★★
“Jennifer and Jackson were outstanding. They both were always available to answer any questions and made my closing easy.”
Nicolas O.
Dallas, TX
★★★★★
“Jackson and team were attentive to what we were trying to accomplish. Jackson was creative and helped to get us to the point of agreement and signing with his ideas.”
Eugene V.
Parker, TX
★★★★★
“Continual updates and quick responses.”
Matthew M.
Aubrey, TX
★★★★★
“He will not issue a pre-approval if he doesn’t think the loan will be a success. I’m truly impressed with his ethics and the responsibility he takes on.”
Barbara Arredondo
Realtor · Clay Stapp + Co
The 25th Hour Promise
$30,000

On-Time Closing Guarantee.

If your loan doesn’t close on or before the agreed closing date for any reason within our control, the seller receives $30,000. It has never been paid.

Why it matters to you
When sellers compare offers, a closing date backed in writing makes yours the safer one to accept.
Why it matters to the seller
Their timeline is protected. If we cause a delay, it costs us, not them.
Why we can offer it
The work is done before the offer is written: income, assets, and credit verified, and the file run through underwriting.
Applies to the loan on your pre-approval letter and is a one-time payment made to the seller within 15 days of closing. All pre-approval conditions must be met and the loan must close by the expiration date (or an approved extension). Not valid if the borrower or seller chooses not to close, or if the delay is caused in whole or in part by reasons beyond the lender’s control. Read the full guarantee
Tools & Resources

Prepare with confidence.

Tools to help you plan before and during your purchase. More are on the way.

01
Get Pre-Approved
Answer a few questions to start your file and see your Buyer Confidence Level.
Coming soon
02
Payment Calculator
Estimate your monthly payment with taxes, insurance, and PMI included.
Coming soon
03
Document Checklist
Everything you’ll need to gather for a full pre-approval, in one list.
Coming soon
Frequently Asked Questions

Good questions to ask.

What’s the difference between pre-qualification, pre-approval, and Fast as Cash Pre Approval?+
Pre-qualification is a starting point based on your application and a review of income and credit. Full pre-approval means your credit, income, employment, and assets have been documented and run through automated underwriting. Fast as Cash Pre Approval means a live underwriter has approved your file, and only property items like the appraisal, title, and insurance remain. Each level makes your offer stronger.
How long does it take to get pre-approved?+
Once we have your documents, a full pre-approval can often be completed within 24 hours.
What documents will I need?+
Typically your last two years of W-2s or tax returns, your most recent pay stubs, two months of bank and asset statements, and a photo ID. If you’re self-employed or have other income, we’ll tell you exactly what else to send.
Will getting pre-approved hurt my credit?+
Starting the process doesn’t require a credit pull. A full pre-approval does include a credit report, and multiple mortgage inquiries within a short window are generally treated as a single inquiry by the scoring models.
How much do I need for a down payment?+
It depends on the loan program. Some conventional loans allow as little as 3–5% down, and some government programs allow less. With less than 20% down on a conventional loan, you’ll usually pay private mortgage insurance (PMI) until you reach enough equity.
What are closing costs, and how much should I plan for?+
Closing costs cover lender fees, title, appraisal, prepaid taxes and insurance, and similar items. A common planning range is 2–4% of the purchase price. You’ll receive an itemized Loan Estimate early in the process so there are no surprises.
How long is my pre-approval good for?+
Your letter shows a “valid through” date, usually 60–90 days. If you need more time, we can refresh your documents and extend it.
How does the $30,000 On-Time Closing Guarantee work?+
If your loan doesn’t close by the agreed date for a reason within our control, the seller receives $30,000. It gives sellers a reason to choose your offer. Conditions apply; see the guarantee section above.
How will I know where my loan stands?+
You, both agents, and the title company get a structured update every week, and you’ll have direct access to Jackson. You won’t have to chase anyone for status.
Can I lock my interest rate?+
Yes. Once you’re under contract, we’ll talk through current rates and the right time to lock. Rates on a pre-approval are estimates and aren’t locked until you choose to lock.
Ready when you are

Start your pre-approval.